How much down payment assistance can you get in Arvada, CO in 2026?
How much down payment assistance can you get in Arvada, CO in 2026?
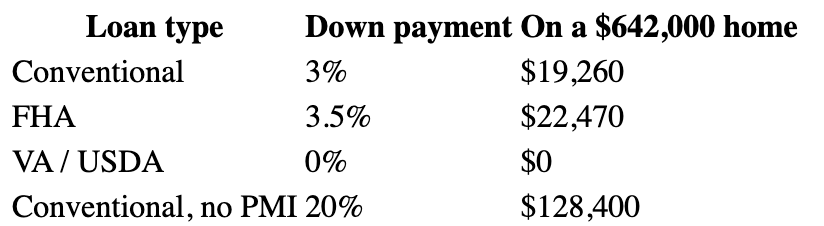
According to North Denver broker Nick Ahrens, first-time buyers in Arvada can stack down payment assistance from CHFA, metroDPA, and county-level programs to cover most or all of a 3% to 3.5% down payment, which runs about $19,260 to $22,470 on Arvada's $642,000 median-priced home. CHFA alone offers up to $25,000 as a grant that never has to be repaid, and because Arvada sits across both Jefferson and Adams counties, the exact program menu you qualify for depends on the home's address, price, and your income. Most buyers use one primary assistance program rather than layering all of them. Figures are current as of September 2026.
By Nick Ahrens | September 16, 2026
Nick Ahrens, a North Denver broker who runs down-payment math with first-time buyers across Arvada every week, tells them the biggest myth is that you need 20% down to buy here. You don't. The bigger question is not whether you can buy with less, it's which assistance program fits your price point, your income, and the county line your future home falls on. Arvada is one of the trickier markets in the metro for this, because the city is split between two counties and its median price sits right at the edge of some program limits.
Figures sourced from CHFA, the City and County of Denver metroDPA program, Freddie Mac, and Redfin, current as of September 2026.
How much down payment do you actually need to buy in Arvada?
You need as little as 3% down on a conventional loan or 3.5% on an FHA loan to buy in Arvada, and VA and USDA loans can require nothing down. On Arvada's $642,000 median sale price, here is what those minimums look like before any assistance:
The Arvada market moves fast. Homes sell in about 22 days and receive 2 offers on average, per Redfin, so buyers who wait to save a full 20% often watch prices move before they are ready. Putting less than 20% down means you carry private mortgage insurance (PMI, the monthly premium that protects the lender on a low-down-payment loan) until you build enough equity, but PMI is often a few hundred dollars a month, not a dealbreaker, and it comes off later.
The 2026 conforming loan limit in both Jefferson and Adams counties is $862,500, so nearly every Arvada financing scenario stays inside conventional loan territory. For most first-time buyers here, the real obstacle is the cash for the down payment and closing costs, not the loan size. That is where assistance comes in.
What down payment assistance programs work in Arvada in 2026?
Arvada buyers have access to five main down payment assistance sources in 2026, and the strongest two are CHFA and metroDPA. Here is the menu:
ProgramWhat you getKey limitCHFA DPA GrantUp to the lesser of $25,000 or 3% of your loan, never repaidIncome up to $130,400 (1-2 person, Jeffco non-targeted)CHFA DPA Second LoanUp to the lesser of $25,000 or 4% of your loan, 0% deferredRepaid on sale, refinance, or payoffmetroDPAUp to 5% of your loan as a 0% second mortgageIncome up to $210,150; no first-time requirementNeighborhoodLIFTUp to $15,000Adams, Arapahoe, Denver, Douglas, Jefferson countiesIDF FirstBank DPAUp to $30,000 or 20% of priceMust use FirstBank; income at or below 80% of area median
CHFA (the Colorado Housing and Finance Authority) is the workhorse. Its grant is money you never pay back, capped at the lesser of $25,000 or 3% of your first mortgage. On a $619,530 loan, which is an FHA purchase at Arvada's median with 3.5% down, 3% comes to about $18,586. That covers most of your $22,470 down payment and leaves a small balance plus closing costs. If you would rather not take the grant's slightly higher rate, CHFA's second-mortgage option gives up to 4% at 0% interest, deferred until you sell or refinance.
metroDPA is the other heavyweight, and it has one feature CHFA's price-limited products do not: no first-time-buyer requirement and a high income ceiling of $210,150. It provides up to 5% of your loan as a zero-interest second mortgage, which on a median Arvada purchase can cover the entire down payment. When Nick Ahrens walks a buyer through a Candelas or Olde Town purchase, this is often the program that gets them to the closing table, because it works for repeat buyers and higher earners who get shut out of the income-capped grants.
The programs do not all stack. Most buyers use one primary source, CHFA or metroDPA, and in some cases layer a smaller grant like NeighborhoodLIFT on top. Your lender confirms which combinations are allowed. If you want the Broomfield version of this program breakdown, I have mapped how the same programs play out in Broomfield, where the higher median changes which ones actually fit.
Does Arvada's two-county split change which programs you qualify for?
Yes. Arvada straddles Jefferson County, which covers most of the city, and Adams County on the eastern edge, and that county line changes your income limits, purchase-price caps, and which local programs apply. This is the detail that trips up buyers who read a generic Colorado down payment assistance guide and assume every program works the same everywhere.
A few ways it matters in Arvada:
CHFA FirstStep and FirstGeneration carry county purchase-price and income caps. Arvada's $642,000 median sits near or above the lower-tier caps, so many buyers here lean on CHFA's no-price-limit products instead. Verify the current county cap with a CHFA-participating lender before you shop.
Adams County adds its own layer: an employer-connected program offering $10,000 toward down payment or closing costs if a household member works for an Adams County employer. Jefferson County buyers cannot use it.
Metro-district taxes vary lot by lot in newer Arvada subdivisions like Candelas and Leyden Rock, and they raise your monthly payment, which affects how much loan you qualify for. Check the Arvada property-tax and metro-district breakdown and verify taxes by parcel, because a higher tax bill can shrink your buying power more than the down payment does.
Pull the exact address before you assume a program fits. A home on the Adams side of Sheridan Boulevard and a home a mile west in Jefferson County can qualify for different help.
What is the catch with down payment assistance in Arvada?
The main tradeoffs are a slightly higher interest rate, income and credit requirements, and a repayment trigger on some programs. None of them are hidden, and for most buyers the math still favors taking the help.
Here is the fine print that matters:
Credit score: Most programs require a 620 minimum, and some want 640.
Income limits: CHFA's cap runs about $130,400 for a 1-2 person household in Jefferson County non-targeted areas, rising for larger households and targeted areas. metroDPA goes up to $210,150. CHFA revised its limits in mid-2026, so confirm the current figure.
Homebuyer education: CHFA, CHAC, and NeighborhoodLIFT all require a homebuyer class, often a few hours online or free in person.
Your own money: CHFA requires a minimum $1,000 of your own funds in the deal.
Rate bump: Assistance loans usually carry a rate roughly 0.125% to 0.5% above market. Over a short hold that costs little; over 15 years it adds up, so weigh it against the cash you are saving today.
Repayment: Grants are never repaid. Second-mortgage assistance is repaid when you sell, refinance, or pay off the loan.
Denver-metro buyers describe the process as worth the paperwork. On r/Denver, buyers call it a pain to navigate but say many closed with only a couple thousand dollars out of pocket. Your qualifying income and monthly payment also depend on your debts and the home's taxes, which is where running your actual numbers with a lender and agent beats any online estimate. If you want to sanity-check what you can afford first, here is how the income math works on a Denver-metro purchase, and here is the full first-time buyer path in Colorado.
Frequently Asked Questions
Do you have to be a first-time buyer to get down payment assistance in Arvada?
No. metroDPA has no first-time-buyer requirement and works for repeat buyers up to a $210,150 income limit. Some CHFA products like FirstStep and FirstGeneration are first-time-buyer programs, but CHFA's Preferred option and metroDPA are open to buyers who have owned before.
What credit score do you need for down payment assistance in Colorado?
Most down payment assistance programs require a minimum credit score of 620, and some require 640. You also complete a homebuyer education class and keep your income under the program's limit.
Can down payment assistance cover closing costs too in Arvada?
Yes. CHFA and metroDPA assistance can be applied to both your down payment and your closing costs, which in Colorado typically run about 2% to 4% of the purchase price for buyers. On a $642,000 home, that is roughly $12,840 to $25,680 before any credits.
How much income can you make and still qualify in Arvada?
It depends on the program and your household size. CHFA's limit is around $130,400 for a 1-2 person household in Jefferson County non-targeted areas, while metroDPA allows up to $210,150. Larger households and targeted census tracts have higher limits.
Is down payment assistance worth it if it raises my rate?
For most first-time buyers, yes. A rate bump of 0.125% to 0.5% costs a modest amount per month, and getting into a home now, in a market where Arvada prices have already moved, often outweighs waiting years to save a full down payment. The longer you plan to hold the home, the more the rate matters, so compare both paths.
Your first move if the down payment is the holdup
Down payment assistance in Arvada can put $15,000 to $30,000 or more toward your purchase, and the right program depends on your income, your credit, your price point, and which county your home sits in. The programs are real, they close deals here every month, and the paperwork is manageable with a lender who uses them often.
If you want to run your actual numbers, what you would need in cash, which assistance program fits, and what you can realistically afford in Arvada, call or text me at 949-230-3625, or email me at NickAhrensRealEstate@gmail.com. I will walk you through your specific situation and connect you with a CHFA-participating lender.
About Nick Ahrens
Nick Ahrens is a Colorado real estate broker with The Apollo Group at eXp Realty, specializing in the Anthem and Baseline communities of Broomfield (80023). With 15+ years in the business and 350+ career closings, he helps North Denver sellers and relocating buyers navigate pricing, timing, and the path to closing. Connect with Nick at youranthemhome.com.